You can use the nominal option to produce a nominal journal for integration with your accounts software. However before you start using this option, you must enter your nominal settings in Sage Payroll so it knows where to post your journals to.
Don’t add commas to descriptions, translations or nominal codes, as these will be interpreted as columns in the CSV file and place data in the incorrect columns. This may result in a failed import into your accounting package.
1. On the menu bar, Click Nominal and Set-up.
2. Specify the format of the nominal codes you want to use in Sage Payroll for analysis of payroll costs.
This field must have an entry, and can be up to 16 characters in length. When you’re defining a format, there are three letters with special meaning:
d – department code
c – cost centre code
a – item code
All other characters are understood by Sage Payroll, in the context of nominal code formats, to be constants.
For example, if you specify the format definition ddddccccaaaa, Sage Payroll expects codes whose first four characters identify the department, the next four characters identify the cost centre and the final four characters identify the item code.
In this example for Sage 50/Instant Accounts, this field must read: aaaaddddd.
3. Complete the following information with the relevant nominal Codes. In this case we have taken the default nominal codes from Sage 50 Accounts:
Nominal Code Format: aaaadddd
Employee PRSI: 2210 [PAYE/PRSI/USC]
Employer PRSI +: 7006 [ER PRSI]
Employer PRSI -: 2210 [PAYE/PRSI/USC]
ASC: 2240 [ASC]
PAYE: 2210 [PAYE/PRSI/USC]
USC: 2210 [PAYE/PRSI/USC]
Bank Account: 2220 [WAGES CONTROL ACCOUNT – NET WAGES]
Rounding Account: Round
Suspense Account: 9998
4. The Journal Format is used to specify the print column positions in the nominal report or file output for the following:
Code – 5
Description – 20
Debit value – 55
Credit value – 65
Total – 85
Example of the Journal when its printed
Click OK when this is complete.
5. Select Nominal – Payments
Set your Payments to 7000 for Gross pay as follows:
6. Select Nominal – Deductions
set you nominals for Deductions as follows:
7. Select Nominal – Departments
In my accounts package my department codes are 1 – 2 – 3 etc so in payroll I have entered in these codes as 001,002 and 003 as follows:
8. Select Nominal – Translations
Set up translations for the balance sheet items as follows:
This table is used to set up alternative nominal codes. This is a useful tool if you want to make the nominal coding structure less rigid. You can use it to translate the codes defined in Payroll to alternative codes that will be used when you export the report or file to import.
So in this case I want my balance sheet codes to be used and not look at the department. If I don’t enter these in here it will split them out by department being:
2210001
2210002
2210003 and so on
Instead we enter in
2210 – PAYE/PRSI/USC
2220 – Wages Control Account
2230 – Pension
2240 – ASC
All the profit and loss nominal will now be split by department.
8. Select Nominal – Descriptions
By default, the nominal report show’s the nominal code, enclosed by square brackets in the Descriptions field. An entry in the nominal report with nominal code 2200 shows [2200] in the Description field. You use the Descriptions feature to replace the nominal codes with text to define what the entry refers to. This can be repeated for all codes created by the nominal process.
You can translate the nominal codes into English as follows:
9. Final Payroll Journal Report
You will now get the following report when you preview it within the payroll.
If you require a more detailed report or you would like to import the file into your accounts package please contact us for a quote to set this up.
Here at Pimbrook, we encounter many ‘Date’ queries at Year End time. We have assembled this article to try to take the mystery out of dates at Year End.
See below a list of questions that we frequently get asked:
What is the ‘Pay Date Rule’?
What do I need to consider when planning my pay periods at Year End?
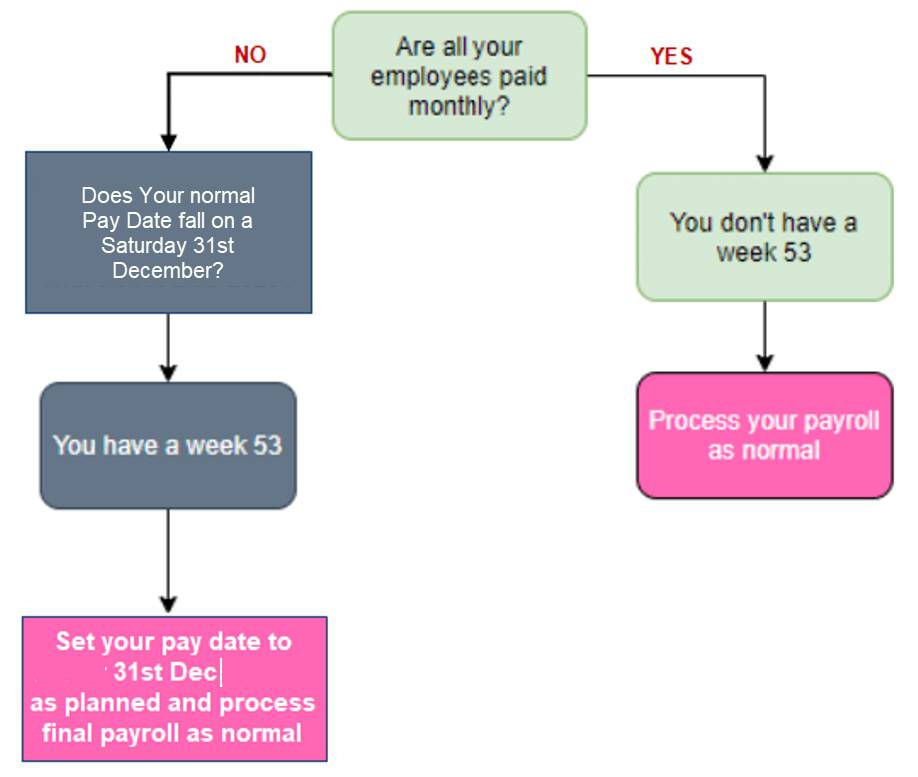
How do I know if I have a Week 53?
What do I need to consider when planning my New Year Calendar?
Is it ok to pay my 2021 Period 1, as the final period in my 2020 Payroll System instead?
1. What is the ‘Pay Date Rule’?
The pay date rule means that if the planned pay date for a period is a 2021 date, then the period belongs in the 2021 payroll and if the planned pay date is a 2022 date, then the period belongs in the 2022 payroll.
All scenarios are governed by the pay date rule.
2. What do I need to consider when planning my pay periods at Year End?
For non-monthly frequency payrolls (eg: weekly, 2 weekly etc..), payments to employees should be on the same day every week – including over year end.
Holiday pay for days taken in 2022 need to be paid using the 2022 payroll. Holiday pay for days taken in 2023 need to be paid using the 2023 payroll.
If you are planning to run the final periods together [eg: Period 51, 52] – the pay date rule still applies.
If you have a Period 53 – it must be run separately, and it must have a paydate of 31/12/2021 – Revenue Requirement.
If you have a Period 53 – Examine the planned pay date for it in your payroll calendar. (Click ‘Company\Payroll’ then click ‘Calendar’ to view it.) If the planned pay date falls in 2022, then it should be included in the 2022 system. The pay date rule still applies.]
If the planned pay date of the latter period, as seen in your payroll calendar screen, falls in 2022, then it should be included in the 2022 This scenario would then require two separate bank payments, one for payment of the 2021 final period(s) and one for payment of the 2022 period. [In this scenario, you can set the bank file execution date to be the same date if required, but you should contact your bank before doing so, as some banks may interpret two files with the same date as a mistake. Alternatively, you can set different execution dates for the two bank files.]
All of the above is irrespective of when the work was carried out.
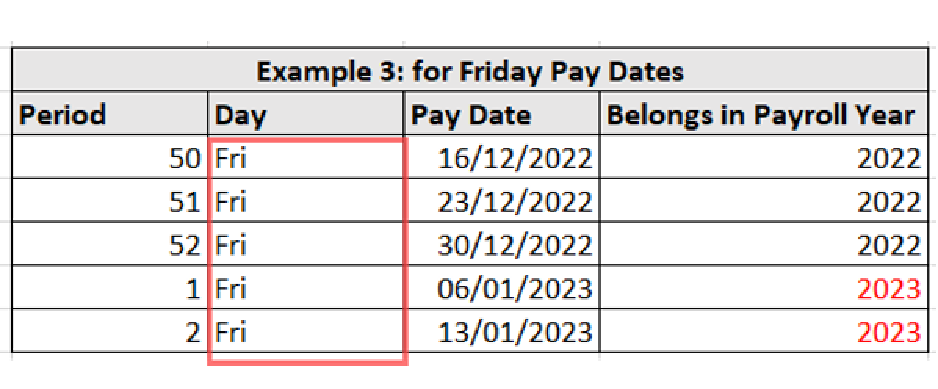
See below Examples of Acceptable Year End 2020/Year Start 2021 Dates: There were 52 Mondays in 2020, 52 Tuesdays in 2020, 52 Wednesdays in 2020, 52 Thursdays in 2020, and 52 Fridays in 2020. The most popular pay dates would generally be Wed, Thurs & Friday. See examples of correct pay dates for those days in the image below. Your payroll may differ of course, but try to stick to the date rules, and plan correctly for 2021.
3. How do I know if I have a Week 53?
Because the number of days in the tax year doesn’t divide into a whole number of tax weeks, any remaining days are known as week 53.
This year (2022), you could only possibly have a week 53 if your Pay Date is on a Sunday or a Thursday, and your final 2020 pay date naturally falls on Wednesday 30th of December or Thursday 31st of December.
If your first pay date of the year was Wednesday the 2nd or Thrusday 3rd of Jan, then you certainly have a Week 53.
Remember here that Revenue want employers to pay on the same day of the week, all year round. This includes over year end.
CAUTION: Whilst many employees may already be on week 1 tax status where your company availed of the Temporary Wage Subsidy Scheme, you must process the extra pay period separately to your penultimate pay period.
4. What do I need to consider when planning my New Year Calendar?
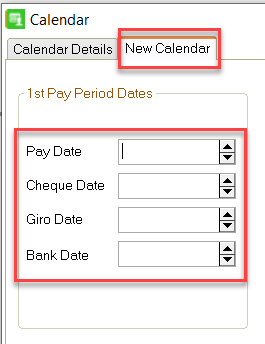
The Period Date & Pay Date fields are key fields in calendar process.
The Period Date field has always been in the system and when setting a new calendar, it is driven by the Period Date field.
Since the Period Date is the systems’ driver when setting up a new Calendar, it’s very important to enter an appropriate ‘Period Date’ for Period 1 of the new tax year, as this date determines all subsequent periods of the calendar.
The Pay Date field was a new addition in 2019, to accommodate payroll modernisation & submissions.
The Pay Date refers to ‘the date the employees receive their net pay’. Revenue use this date to determine when you paid your employees.
Revenue do not use the ‘Period Date’ to determine this, as is sometimes assumed.
Revenue do not receive the Period Date in submissions, they only receive the Pay Date.
With regard to the Pay Date: if you’re on a weekly payroll, your first Pay Date should fall between 1 – 7 January. For a fortnightly payroll, it should fall between 1 – 14 January.
We recommend to keep your Period Date the same as your Pay Date, unless you have a specific reason not to. Make sure you have 52/53 planned periods in your new calendar, and that all the Pay Dates are dated in the new year (ie: 2022).
6. Is it ok to pay my 2022 Period 1, as the final period in my 2020 Payroll System instead?
The short answer is No. Since payroll modernisation came in at the start of 2019, Revenue have been very clear that the do not want you to do this.
Revenue want employers to pay on the same day every period, so changing the pay-day is not an option.
If you remember back to the TWSS it was rolled out in two phases: The Transitional Phase (26th of March – 3rd of May), and the Operational Phase (4th of May – 31st August).
During the Transitional Phase the employer was expected to calculate the Average Revenue Net Weekly Pay and pay the correct subsidy to the employee via payroll. During this period Revenue refunded employers the maximum subsidy amount of €410 per qualifying payslip, per qualifying employee, per week (or in multiples of this for other pay frequencies). While payroll systems recorded the employees specific TWSS payment amount against a specific payment name, those systems were not yet reporting the exact subsidy amounts back to Revenue via submissions. Things were fast paced back then.
During the Operational Phase, this worked a little differently: Revenue provided employers with the relevant employee information (CSV download) to ensure the correct subsidy amount was paid to each employee, and refunded to the employer on that basis, Payroll systems’ were updated to help decide the exact amount to give to an employee, but also to report back those amounts officially as subsidy amounts, so refunds to employers were from that point more exact.
To tally up the whole thing, Revenue now require employers to carry out a ‘TWSS Reconciliation’. This will be done with the aid of the ‘TWSS Reconciliation’ Feature which came in in Sage Payroll Version 23.3. When you run the feature, it will update the employees ETP records with the actual TWSS values paid to them via nominated Pay Elements in your system. The feature will also create a CSV file, which will list the TWSS payments actually paid to employees during that time. You must then upload the resulting CSV file to the ROS Website to complete your TWSS Reconciliation.
TWSS Reconciliation Upload Window & Penalties:
TWSS Reconciliations must be carried out and uploaded to the ROS website between 21st Sept 2020 – 31st Oct 2020. If you do not provide this data about payments to your employees, Revenue will recoup from you the total temporary wage subsidy paid and related interest charges.
To Process the TWSS Reconciliation in Sage Payroll: Before you start the TWSS Reconciliation process:
Ensure your software is at least on version 23.3 of Sage Payroll
Check the payroll status is Start of Period (SOP) – If its not, the feature will give an error message and will not run.
Check the Employer registration number is entered in Company Details.
Ensure a recent payroll backup has been taken to a safe location.
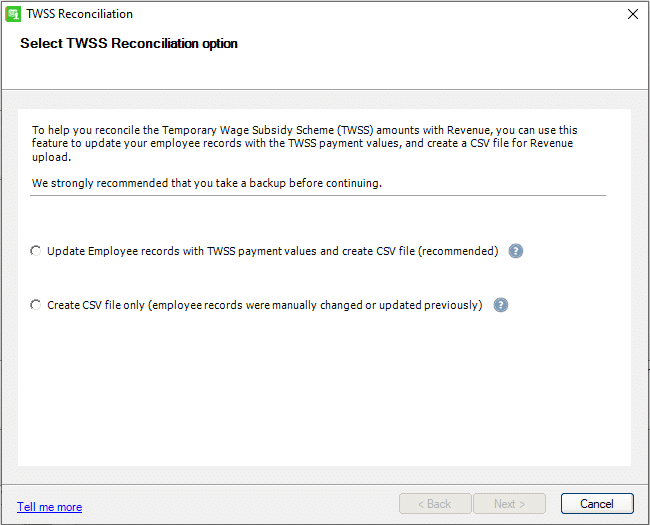
To start the process – at the top of the main screen click on Miscellaneous\Covid-19\TWSS Reconciliation. This will present the TWSS Reconciliation Wizard.
There are two options depending on what stage of the process you are reconciling your values with ROS:
Update the employee records with TWSS amounts paid during transitional phase, and create a new CSV file (for upload to ROS)
If you use this option in Sage Payroll, the Covid-19 field in the ETP records update, for each relevant employee with the values processed in each period, then creates a CSV file ready for upload to your ROS account.
Create CSV file only, as employee records were manually changed or updated previously by you.
If you use this option in Sage Payroll, it creates a CSV file ready for upload to your ROS account. Use this option if you have previously manually updated the Covid-19 field in the ETP tab for each relevant employee, or completed the Update the employee records and create a new CSV file option already, but now need another copy of the CSV file.
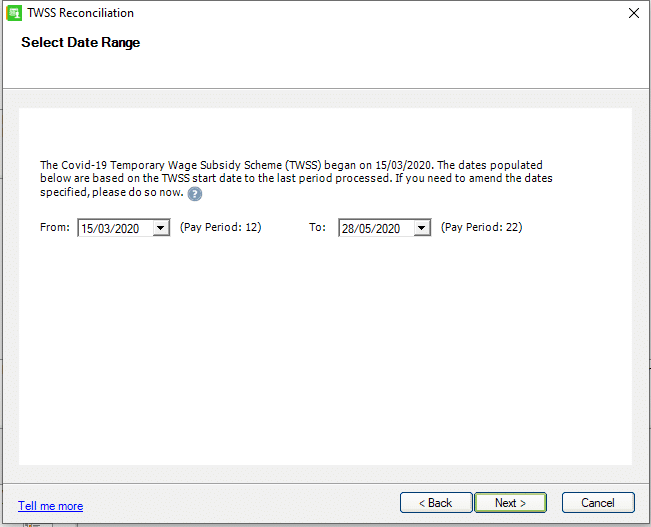
Select Date range used for TWSS subsidy payments:
If you choose the first option, you will be asked to choose a Date Range. The Revenue Covid-19 support schemes (Covid Refund Scheme and TWSS) came into effect from March 15, meaning a date previous to March 15 should not be selected within the reconciliation wizard, but you can do so if required.
Select payments used to process subsidy: To ensure the correct values are used to update each employee’s ETP record, select the appropriate payments in the list – at least one payment must be selected to proceed in the wizard.
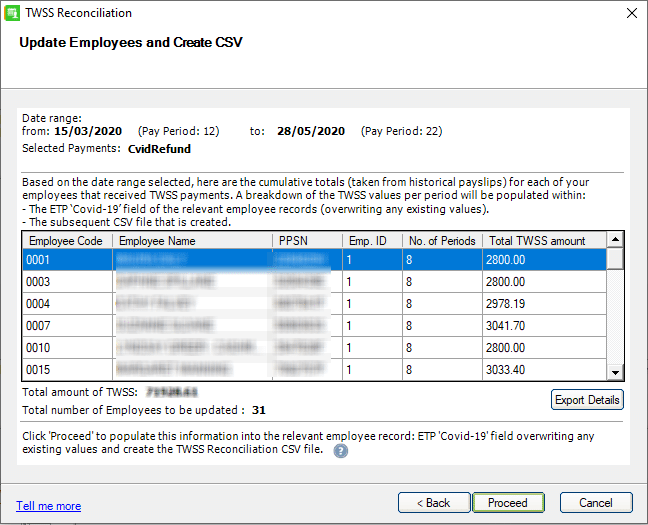
View Employees to Update:
The wizard will present a list of the relevant employees whose ETP records it is about to update:
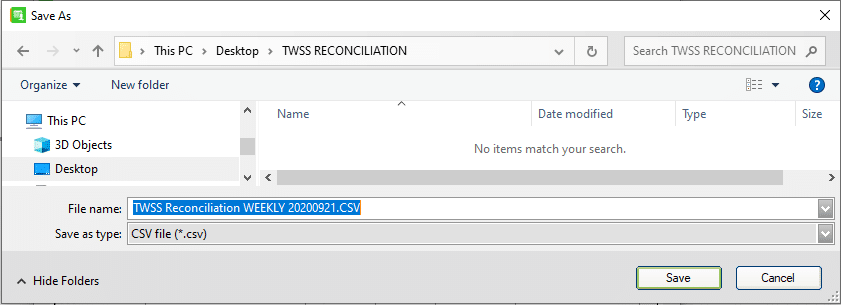
Save Reconciliation CSV File: The next screen will prompt you to save the file to a chosen location. Make a note of the location as you will need it later when you are uploading the file to ROS.
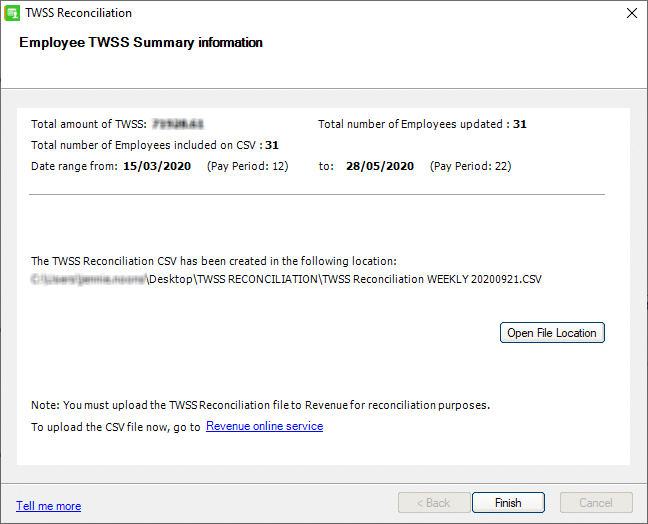
Update Employees & Create CSV File:
Once you click Save, the employee records are updated and the CSV file is created. It is ready for upload to the ROS Website.
Uploading the TWSS Reconciliation CSV File to ROS:
Page 3 of Revenues publication “Instruction on Uploading and Reviewing Subsidy Paid Data via CSV” contains instructions on how to upload the TWSS Reconciliation CSV file to the ROS website.
You can link to the publication here.
More information on the TWSS Reconciliation can also be found at the following links:
Sage Full Article: “Covid-19 TWSS Reconciliation” –> Click Here
Sage Payroll update version 23.4 is now available.
**Important Note: If you are using the CWPS Feature in Sage Payroll, you should refrain from installing this update until on or before Monday 28th September! This update contains the new rates which pertain to the new CWPS year (CWPS New year starts on 1st October. Monday 28th Sept is the start of Week 1 of the new CWPS year.)
What’s New:
New CWPS rates, (come into effect on the 28th of Sept). Link to full article here –> CWPS New Calendar
Timesheet warnings with regard to EWSS, when the Gross Pay/Insurance weeks are outside of the allowed range. Link to full details here –> EWSS TImesheet Warnings.
Timesheet EWSS information flag, to indicate when an EE is marked for EWSS.
Installing the Update: You may be prompted to install the update from your Sage Payroll software, if not you can download and install it from the Pimbrook download area. The procedure for this is the same as with any prior payroll update – see notes below:
Ensure you have the correct version of software for the update. To see the version, open Sage Payroll 2020, click Help then click System Information. The current version should be V23.3
In the System Information Screen, make a note of the Program Directory and Data Directory.
Check that all of your payrolls have a status of End of Period (EOP) or Start of Period (SOP).
Back up your payroll data.
Close Sage Payroll 2020 and all other software.
Log in to the computer as administrator (or as a user with administrator rights) and turn off any anti-virus and “User Account Control”.
Download the update from the Pimbrook Download area by clicking here.
Execute the downloaded file and follow the install steps, ensure the program and data directories are the same as noted in 2 above, for more information see our article on Sage Payroll Update Instructions and Preparation.
Important Note:
Please ensure that you install the update correctly, particularly if you are using a network installation and the data location is not on the same computer. If you find that some employees are on PRSI class A1 regardless of their PRSI eligible pay then you probably have not applied the update to your data location (i.e. the server). If this occurs please reinstall the update correctly to all required locations (i.e. client and server computers).
To avail of Revenues EWSS July/Aug Sweepback you must upload a CSV file to the ROS website. The file must contain a list of EWSS eligible employees who were paid during July & August 2020. You can generate the employee data either manually or by a report in your Sage Payroll Program. You must then upload the resulting CSV file to the ROS Website.
On 15 September 2020 Revenue released a facility on ROS where an Employer can upload this Sweepback CSV. All applications must be submitted by the employer or agent through Revenue Online Services before 14 October 2020.
To Generate Employee Information Manually:
You can download a template from the Revenues website & fill it in yourself. The file is available on this Revenue page: Revenue Sweepback. When you have entered all the relevant information, you must save the file as a CSV file, and then upload that to the ROS website.
Generate Employee Information by Sage Payroll Downloadable Report (ARW): If you don’t want to generate the information manually, you can download an ARW report which can be saved into your Sage Payroll program. This report will generate a list of employees with pay dates between 01/07/2020 – 31/08/2020. You can link to the full article here, which contains a download link to the ARW Report and instructions on how to save & run it in Sage Payroll (Advanced Report Writer). The file generated can then be saved as a CSV file, and finally be uploaded to the ROS website.
Upload the Sweepback CSV File to the ROS Website:
Page 5 of Revenues publication “Guidelines on the Operation of the July/August Sweepback as part of the Employment Wage Subsidy Scheme” contains instructions on how to upload the Sweepback CSV file to the ROS website. You can link to the publication here.
NOTE: Depending on your Internet browser, the file automatically downloads to your Downloads folder or you’re prompted to save the file.
Once the report downloads, save it into the data directory of your payrolls. To access the data directory, in Sage Payroll, browse to Help > System Information > click the blue link under Data Directory. TIP: If the report is saved into the Data Directory, the report will be automatically picked up ARW.
Run the report
From the Windows desktop, open ARW 2020. NOTE: If there is no icon for ARW 2020 on your Desktop, please view this guide > Read More >
When prompted to log in, enter the same log in details as you do to open Sage Payroll then click Ok.
The government have introduced an extended Wage Subsidy Scheme in the form of the “Employment Wage Subsidy Scheme” otherwise known as the EWSS. The scheme provides a flat-rate subsidy to qualifying employers based on the numbers of paid and eligible employees on the employer’s payroll. It came into effect on the 31st July 2020 and it replaces the Temporary Wage Subsidy Scheme (TWSS) which has been in existence since the 4th May 2020. The EWSS is expected to run until the end of March 2021. Both schemes will run in parallel from 1 July 2020 until the TWSS ceases at the end of August 2020. The eligibility particulars for the EWSS are different to the TWSS, so if you didn’t qualify for the TWSS, there is a chance that you will qualify for the EWSS.
We have outlined the main points from this below, but please refer to the Revenue article for full details –> July Job Stimulus (including EWSS).
Joining the EWSS:
If you didn’t qualify for the TWSS, but you qualify for the EWSS, you must join the EWSS scheme from the ROS Website. This can be can be done as follows:
Ensure your company has a valid Tax Clearance Certificate. (If not go to “ROS > My Services > Other Services > Manage/Verify Tax Clearance”).
Register for EWSS on ROS under “My Services > Other Services > Manage Tax Registrations > Employment Wage Subsidy Scheme > Register > Accept Declaration”
How Will the EWSS Effect Payroll Processing?
Under the EWSS the processing of payroll will return to the normal manner (i.e. calculating and deducting Income Tax, USC and employee PRSI through the payroll). As the EWSS beneficiary is the employer, there will be no visibility of it on payslips and employers PRSI will remain at 0.5% (as per the TWSS),
The employee will however need to be flagged in the software as being part of the EWSS, because of this, there will be a software update released for Sage Payroll (version 23.3) on or before the 1st of September. You will be able to get this via your payroll software (Help > Check for Updates) and we will add a link here when it is available..
In your Sage Payroll, set your period after the 1st of September.
Go to “Miscellaneous > COVID-19 > Edit Employee EWSS/TWSS Setup”.
Select the option that best matches your requirement (you can change individual employee records for exceptions to this afterwards).
– Change all employees…
– Disable all employees…
– Enable all employees….
Amend individual employee records for exceptions to the above under the “Payment” tab.
Ensure your employees are on the correct scheme and PRSI code (under the “Employee Record”).
Claiming EWSS for New Hires and Seasonal Workers:
Eligible employers may backdate a claim to 1 July 2020 for EWSS payments in respect of new hires and seasonal workers, subject to limited exceptions. Payments in respect of July and August are expected to be made by Revenue in mid-September, with payments for subsequent periods being made monthly in arrears thereafter. Further guidance and information for employers on how to make applications for new hires and seasonal workers will be available soon.
What Will the New Subsidy Rates Be?
Under the EWSS, eligible employers will receive a per-head subsidy on a flat-rate basis which will be determined based on the amount of gross pay that the employer pays to the eligible employee as shown in the table below. Payments to employers will be made monthly in arrears.
Eligible employers may backdate a claim to 1 July 2020 for EWSS payments in respect of new hires and seasonal workers, subject to limited exceptions.
Non-TWSS employers, who have not previously availed of TWSS, will only be eligible to apply for the EWSS.
TWSS employers will still be able to rehire eligible employees and continue to operate TWSS to 31 August 2020.
To qualify for the EWSS, you must be able to demonstrate: that your business will experience a 30% reduction in turnover or orders between 1 July and 31 December 2020 and that this disruption is caused by COVID-19.
This reduction in turnover or orders is relative to:
The same period in 2019 where the business was in existence prior to 1 July 2019.
The date of commencement to 31 December 2019 or;
where a business commenced after 1 November 2019, the projected turnover or orders.This reduction in turnover or orders is relative to:
Self Assessment: To ensure you continue to meet the above eligibility criteria, you’re required to undertake a review on the last day of every month to ensure you continue to meet the above eligibility criteria, and if you no longer qualify, you should de-register for EWSS.
If your company is currently taking part in the TWSS and you want to continue receiving Wage Subsidies, you will be obliged to switch to the EWSS on the 1st Sept 2020. The EWSS replaces the TWSS from this date onwards. Switching is not automatic and you will need to apply for the EWSS on the ROS website.




 NOTE: Depending on your Internet browser, the file automatically downloads to your Downloads folder or you’re prompted to save the file.
 TIP: If the report is saved into the Data Directory, the report will be automatically picked up ARW.
