• Payroll Year End 2026
    See our Webinars

KB Category: Sage Payroll (Micropay)

Sage Payroll – Returning To Work After Covid-19 Lockdown/Layoff

With the easing of COVID-19 restrictions and the country now entered into phase 3, many businesses which have been closed will be re-opening. Whether your business has been completely closed for a while and your payroll has been fully inactive, or you’ve been partially opened with some staff on the payroll, its likely that you will be re-joining some or all staff to the payroll shortly. If this applies to you then there are a few things to consider before moving forward with your next pay period. This article will touch on the various scenarios you might find yourself in, and endeavor to steer you in the right direction.

Return to Work Process:
Whether your returning some or all of your employees to the payroll, the process will involve the steps listed here. See notes further down pertaining to each step.

  1. Check Your Sage Payroll Software Version
  2. Advise Returning Employees to sign off the Pandemic Unemployment Payment
  3. Check Employee Status
  4. Re-Instate Leavers (Where Necessary)
  5. Joining the Temporary Wage Subsidy Scheme?
  6. Download Employee RPN’s
  7. Enter Time & Pay
  8. Submit the Payroll to Revenue
  9. Leaving the Temporary Wage Subsidy Scheme.


1. Check Your Sage Payroll Software [Full] Version No:

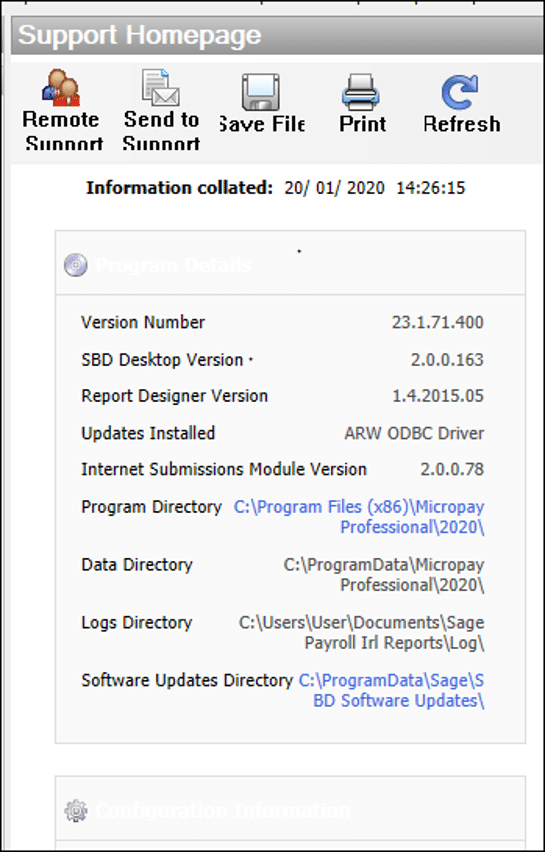
The current full version number of Sage Payroll is V23.2.76.601 (also referred to as build number) Whether your re-activating your payroll after months of being off, or simply re-joining staff to your already active payroll, you will need to make sure you are on this version number. To check this simply log into you software, then click Help\About from the menu bar at the top of the screen. Lots of information will be displayed, but the first item in the list is ‘Version Number’. This is the number you need to check. If your version number is already 23.2.76.601, then you don’t need to do anything. However if you are not on version 23.2.76.601 then you need to update your software before processing your next period. You can download the 23.2.76.601 update here For instructions on how to apply the update see our previous article: Update Sage Payroll (Micropay).


2. Advise Returning Employees to Sign Off the Pandemic Unemployment Payment (PUP):

In all cases, where the employee had been claiming the PUP directly from the DEASP for the duration they had been off work, they now need to sign themselves off of that payment. Click here to read full details of how to do that on the Gov.ie website.


3. Check Employee Status:

You need to check employees to see what their current status is. You need to identify whether the employee was officially terminated in the payroll [or not] after their last payment in this payroll. Some payroll operators will just know what the status of each employee is, but if you need to check this, simply click Edit Employees, choose the employee in question, and click on the ‘Tax/PRSI/USC’ Tab at the top of the screen. Check if the Finished Date & Finish Period have been filled in. Depending on whats filled in, each employee will be either: Not Teminated, Suspended or Terminated.

  1. Not Terminated: If the Finish Date is empty and the & Finish Period is zero then it means that the employment was not officially terminated. There is no action need here, just process payment for the employee as normal.
  2. Suspended: If the Finish Date is empty and the & Finish Period is ’99’ then it means that the employment was suspended. To remove the suspension, simply remove the ’99’ from the Finish Period, save the employee and then process payment for the employee as normal.
  3. Terminated: If the Finish Date & Finish Period field are filled in, then it means that the employee was officially terminated. This will have been conveyed to Revenue during a submission. The action needed here is to re-instate the employee before processing payment for the employee. See note below on how to re-instate a leaver.


4. Re-Instate Leavers (Where Necessary):

You can re-instate a leaver by either using the ‘Re-Instate Leaver’ feature under the Processing menu at the top of the screen, or by editing certain fields directly in the Employee Details. Both methods are explained in this Sage Article here. A point to note when re-instating a leaver is that the Employment ID must be incremented after re-instating. This is a requirement by Revenue.


5. Joining the Temporary Wage Subsidy Scheme?
If your business is joining the Temporary Wage Subsidy Scheme now, then at this point you need to read through our previous article regarding Processing Payroll under the Temporary Wage Subsidy Scheme to familiarise yourself with the process. After working through that article, return to this point and continue on in this process. Click here to open our previous article. You will also need to familiarise yourself with the contents of Revenues TWSS Operational Guide & FAQ Document, which can be accessed here. This document is continuously being updated by Revenue.
If your business is already processing payroll under the Temporary Wage Subsidy Scheme and you are familiar with the process, at this point you need to import the Revenue Average Net Pay from your ROS file, for returning employees.


6. Download Employee RPNS:
Download employee RPNs as usual. If your software encounters an issue communicating with the ROS system, first check if you can login to the ROS website. If you cannot login  to the the ROS website then investigate if there is an issue with the ROS system or with your ROS cert. If you think your ROS cert has become out of date, you can follow the instructions here to renew your ROS digital cert.
We can advise that we have seen in recent weeks where there were no RPNs available for employees where the payroll operator was expecting a new/updated RPN. In some of these cases employees had seen more than one employment listed for the same employer in their ‘MyAccount’ at Revenue. Employees should make sure that the correct employment is the ‘active’ one, and that their tax credits are assigned to that one.


7. Enter Time & Pay:
You can enter Time & Pay in your normal way, whether that be manual entries or by file import. If the employee has not been paid for a while then you could expect some refund of statutory deductions  in this period. (eg: Tax, USC). Please note that from the 20th June 2020, Revenue have been issuing RPNs on a Week1 basis. A Week 1 tax status will disallow refund of statutory deductions (Tax/USC), in an effort to reduce the impact of the re-payment of tax/USC by the employee at the end of the year.

8. Submit the Payroll to Revenue:
When your payments are complete and you are happy with your payroll, you can submit your payroll to Revenue using the ‘Send Payroll Submission’ button. If you are processing under the Temporary Wage Subsidy Scheme for the first time please be aware that Revenue are not in support of re-submissions of payrolls containing Wage Subsidies. If you find yourself needing to carry out a re-submission at any point, you will need to discuss this with revenue first.

9. Leaving the Temporary Wage Subsidy Scheme:
We are noticing some business now leaving the Temporary Wage Subsidy Scheme. Employers who no longer wish to avail of the TWSS, should cease returning J9 PRSI Class payroll submissions to Revenue. Employers should also inform Revenue via MyEnquiries of their intention to exit the scheme and ensure the employee J9 PRSI Class (J9 submissions) is reverted on future payroll submissions for each employee to their normal PRSI class (Pre-Covid-19). Those employers who have stopped participating in the TWSS will be included in the reconciliation phase of the scheme and will be included in the list of TWSS participants published at the end of the scheme. If the business as a whole is leaving the scheme, be sure to un-tick the Covid-19 tickbox on the Covid-19 subsidy pay element in the pay elements list. You can access the list from the Company/Payroll option at the top of the screen, then choose ‘Payments’. You should also remove the formula from the Formula’ field to stop the subsidy amount from automatically calculating on timesheets.
Sage Payroll Software Update 23.2 for Operational Phase of the Covid-19 Temporary Wage Subsidy Scheme (04/05/2020 – 31/07/2020)

Important Note! 01/08/2020:
The article below pertains to the ‘TWSS’ (Temporary Wage Subsidy Scheme). The ‘TWSS’  closed for new applications on 31st July 2020. It has been replaced by a new scheme called the ‘EWSS’ (Employment Wage Subsidy Scheme). Companies who are currently in the ‘TWSS’, can remain in it until 31st August 2020, at which point they must switch to the new ‘EWSS’ scheme. Companies who are joining the Wage Subsidy Scheme for the first time (after the 31st July) must join the ‘EWSS’ scheme. The full details of the new ‘EWSS’ scheme have not yet been released by Revenue, however they have released some general info on Gov.ie which you can link to here: EWSS on Gov.ie


What Happened from the 4th of May 2020?

From the 4th of May 2020 Revenue entered the ‘Operational Phase’ of their Temporary Wage Subsidy Scheme. This is be a more real-time approach to processing the wage subsidies.

To kickstart that, Revenue activated a new download feature inside ROS. Employers can download an ‘Average Pay’ CSV file, which they will then need to import into their payroll software. This will ‘set’ the ‘Average Pay’ amount for each employee, into the Employee’s Record. WHile the content of the file will not change much, you can download the file each pay period to catch any changes that may have occurred. The process is similar to that of the way we used to import P2C files from Revenue. (Download a file from ROS, Save It, Open your Payroll Software, Import the File).

In conjunction with the file download, and to accommodate the Operational Phase, Sage released a software update for Sage Payroll on the 4th of May 2020. The new version is V23.2. You will need to be on that version to correctly process payroll under the Wage Subsidy Scheme from the 4th of May 2020 onwards.


With Regard to the Temporary Wage Subsidy Scheme, What does Sage Payroll Software Version 23.2 contain?

The new software version 23.2 contains:

  • A flag to officially nominate your ‘Covid 19’ pay element as your Subsidy payment element. (New Tickbox)
  • A feature to import the Revenue ‘TWSS Calculation’ CSV file, and automatically set the Average Weekly Pay into the Employee’s record. (New field)
  • A flag to mark an employee as being paid under the subsidy scheme. (New Tickbox)
  • A new feature built into the timesheet screen, to automatically calculate the subsidy amount. (New Feature)
  • A new feature built in to the timesheet screen to assist with ‘tiering & tapering’ as you enter in a top up amount. (New Feature)
  • A new field in the Employee ETP record, to hold the Covid19 subsidy amount processed for any applicable period. (New Field)
  • Inclusion of the Covid19 Subsidy payment amount, for each employee, in the live submission to ROS. (Live Reporting)


How do I process payroll under the Temporary Wage Subsidy Scheme?

Before starting the procedure below, please read through all of steps 1-7.
To process payroll correctly under the Temporary Wage Subsidy Scheme, from the 4th of May 2020, you will need to do the following:

  1. Download your ‘TWSS Calculation’ CSV file from your ROS account, and Save it to your PC. See instructions on how to download the file from ROS in the ‘Other Info’ section further down.
  2. In Sage Payroll – Set new period & Take a Backup (Start of Period is the best time to install an update)
  3. Download & Install the Sage Payroll 23.2 Update if you have not done already –> Click Here To Download (212MB). For instructions on how to apply the update see Update Sage Payroll (Micropay).
  4. In Sage Payroll – Open your Payments List and officially mark your Covid19 Pay Element, as a ‘Covid 19’ payment with the new tick box.
  5. In Sage Payroll – Import your Revenue Average Pay CSV file and select the relevant employees to include in the scheme. This will set the ‘Revenue Average Net Pay’ per employee, and save it in a new ‘Revenue Average Net Pay’ field in the employee’s record. (To do this – use the new ‘Covid-19 TWSS Revenue Import’ option under the Miscellaneous menu at the top of the screen. If you get the error “Invalid CSV file selected” when importing, see more help below –> click here)
  6. Important Note: If you have payroll with a frequency of Bi-Monthly or 4-Weekly, you will need to manually add a formula file to your Sage Payroll system. See instructions on how to do this in the ‘Other Info’ section further down. If you don’t have a Bi-Monthly or 4-Weekly frequency payroll, just skip to number 7 below.
  7. In Sage Payroll – Open the time sheets screen and process your time sheets. If you have successfully imported your ‘TWSS Calculation’ CSV file, then you can expect your Covid 19 payment to be automatically populated with the max covid payment allowed for the employee in question. You will need to enter the Top Up payment manually. If you enter an amount which exceeds the maximum top up allowed, then the subsidy amount will automatically taper down (reduce).
  8. In Sage Payroll – When all your timesheets are complete and your payments are saved, you should crosscheck your calculated Covid Subsidy amounts with those in the Revenue CSV File. To do this use the Sage Payroll payments report for the Covid-19 Subsidy pay element, and cross check it with the Revenue CSV file. These could be different due employees having multiple employments, and if so, will need to be corrected in Sage Payroll before submitting to Revenue.
  9. In Sage Payroll – Validate that all employees for whom you are claiming a Covid Subsidy refund for, have been included in the submission. In the submission screen, before you click the final submit button, the total Covid Subsidy amount included in the submission will be shown. You need to check this value against the total value in the Sage Payroll payments report for the Covid-19 Subsidy pay element (used in Step 8). If they don’t match, investigate if you have omitted to apply a taxable top-up value of at least 0.01 cent to one or more employees.

The above steps are demonstrated in our short video –> click here to view.
If you prefer to have a read through, you can link to Sage’s detailed Knowledge Base Article Here –> click here to open.


Other Info/Links:


New Covid Section of the Revenue Website –> Click Here
In the new Covid Section of the Revenue Website, you can download the following:

  • [PDF] Guidance on Employer Eligibility
  • [PDF] Guidance on the Operational Phase of the TWSS  (Effective from 04/05/2020 onwards)
  • [XLS] MS Excel TWSS Sample Subsidy Calculator
  • [CSV] TWSS – Sample Employer CSV File
  • [PDF] TWSS – Employer CSV Description
  • [PDF] Guidance on the Transitional Phase of the TWSS


How to Download Your ‘TWSS Calculation’ CSV File:
This is detailed in section A2.2 of Revenues ‘Guidance on the Operational Phase of the TWSS’ Pdf Document V9 which is linked above, but in short the instructions are:

  • Log in to your ROS Account –> Click Here
  • From the homepage, in the ‘Employer Services’ section click on ‘Request RPNs’
  • On the next screen, click on ‘Request Temporary Wage Subsidy Scheme Calculation’
  • On the next screen, click ‘Request Calculation’ button.
  • On the next screen, enter your password & click ‘Sign & Submit’ button.
  • Look for the file in you ‘Downloads Folder’ on your computer.


Payrolls with Bi-Monthly or 4-Weekly Frequencies:

Sage Payroll V23.2 uses formulae to calculate the Covid19 Subsidy values. Each formula is lengthy and is held in a file in your system data folder. The formula file is then referenced in your Covid19 pay element. Each frequency has a separate formula file. Sage Payroll version 23.3 automatically included the relevant formulae files for the most common payroll frequencies (Weekly, Monthly & Fortnightly). However, for the payroll frequencies Bi-Monthly and 4-Weekly, Sage were unable to include the formulae files with the 23.2 update installation. These have to be added manually. To do this follow the instructions below – you will need to carry out these instructions for each Bi-Monthly and/or 4-Weekly payroll in your system:

  1. Download the appropriate formula file for your pay frequency: Click here to download the Bi-Monthly formula file (CovidB.FML). Click here to download the 4-Weekly formula file (Covid4W.FML).
  2. If prompted, browse to where you want to save the file to (eg: Desktop). If not prompted – check your Downloads folder for the downloaded formula file.
  3. When you’ve located the downloaded formula file, right click on it and the click ‘Copy’.
  4. Open Sage Payroll and log in to the payroll in question as normal.
  5. From the menu bar – click Help\System Information, then click on the Data Directory link.
  6. When the data directory location opens, right click and then click ‘paste’ to paste the relevant formula file to your payroll data location.
  7. Next, you need to link the formula file to your covid payment: In Sage Payroll, from the menu bar – click Company/Payroll then click Payments. Double click on your covid subsidy payment to edit it.
    1. In the ‘Formula’ field at the very bottom of the screen presented, type in the appropriate formula and then press Save: include the quotation marks that you see in the bold text below:

For Bi-Monthly frequency payrolls type: program “covidb.fml”
For 4-weekly frequency payrolls type: program “covid4w.fml”

Note: If you cannot find a ‘Formula’ field at the bottom of the payment screen, it may be because you have ‘Sage Payroll Lite’ In this scenario, for assistance with adding the formula to the payment, please call us.


System Requirements for Sage Payroll:

To view the system Requirements for Sage Payroll –> Click Here


How to Fix Error “Invalid CSV file selected” when using the “Covid-19 TWSS Revenue Import”:

We have had a number of reports from clients saying that the “Average Pay CSV file” form Revenue fails to import into Sage using the “Covid-19 TWSS Revenue Import” function with the error “Invalid CSV file selected”. This seems to be related to how the file was downloaded from Revenue. If this occurs follow these steps to fix the problem..

1. Open the Revenue CSV File,
2. Go to the last employee row and go to Column U
3. Press “Return” to go to a new row.
4. Select “File – Save As”
5, Ensure the “Save as Type” is “CSV (comma delimited)”.
6. Try the import into Sage Payroll again.


How to Fix Error on Opening ARW (Advanced Report Writer):

The most common errors which occur when opening the ARW program are: “Data Source Error Filling Lattice” and “Cannot Read User File”. Either of these can occur if the computer that you’re trying to run ARW on, doesn’t have the required ODBC driver installed on it. To fix an occurrence of either of these download & install this ODBC Driver.


–> Back to instructions

COVID-19 – Updates on Payroll Related Information

Introduction

This article is to highlight changes to the COVID-19 Payroll information that we originally published on the 23/03/2020 – see COVID 19 – Payroll Related, Coronavirus Information.

As this is a rapidly changing area we advise you to revisit this article on a regular basis to keep up to date with the information in it and the related linked articles from Government, Revenue and Sage.

To assist you with this, we have highlighted below the most recent updates that we think are important.

Wage Subsidy Scheme


Introduction of the “Employment Wage Support Scheme” (EWSS) – July 2020

The Employment Wage Support Scheme (EWSS) was announced on the 23rd of July 2020. it replaces the Temporary Wage Subsidy Scheme (TWSS) from the 1st of September 2020 and is expected to be in place until the 31st of March 2021. Both schemes will run in parallel until the end of August 2020 when the TWSS ends. The main features are:

  • Employers can qualify if they can demonstrate that turnover or orders reduced by 30% or more between 01/07/2020 and 31/12/2020 compared to the same period in 2019 and that this was due to disruption caused by COVID-19.
  •  Employers must review this qualification each month to ensure eligibility.
  •  There are exclusions for certain categories of employers.
  •  Administered by Revenue on a “self-assessment” basis.
  •  Subsidy support levels:
    • Gross weekly wage less than €151.50 = Nil
    • Gross weekly wage from €151.50 to €2202.99 = €151.50
    • Gross weekly wage from €203 to €1,462 = €203
    • Gross weekly wage over €1462 = Nil

Sage has released an update to their Payroll software to support this, for more details, see our article –> Processing the Employment Wage Subsidy Scheme (EWSS) in Sage Payroll

You can also get more information from Revenue here –> https://www.revenue.ie/en/corporate/communications/covid19/employment-wage-subsidy-scheme.aspx


April 2020 Updates

Since the Revenue first issued their guide on their “Temporary Wage Subsidy Scheme” on the 26th March 2020, they have continued to add sections to it to bring clarity to certain topics. Queries to them via phone or ‘My Enquiries’ shine a light on certain topics which may need more detail, so it’s likely that they may continue to add clarity/detail to more topics in the near future. Since its original version, it has had 4 revisions.

We have supplied the link to Revenues Operational guide at the bottom of this article. We would advise you to save the link, and check back on it on a daily basis, in order to keep yourself up to date with any new particulars.

Below are examples of items which they recently added some clarity.

[Section 1.6 – What is an additional taxable payment under the Temporary Wage Subsidy Scheme?]
“Sometimes referred to as ‘top-up payments’, an employer can choose to make an additional payment to the employee to fully or partially make up the difference between the amount provided by the subsidy scheme and the employee’s Average Net Weekly Pay. Such additional payments, which cannot be regrossed, are regarded as gross pay and liable to Income Tax and USC. If the employer makes an additional payment greater than the difference allowed by the scheme (i.e. the employee receives more than the Average Net Weekly Pay) then the subsidy value refundable to the employer will be reduced by this excess amount when the refund reconciliation is performed by Revenue in due course.”

[4.4.2. Example 2 – Impact of Additional Payment on Subsidy:]
“An employee is paid weekly and has an Average Net Weekly Pay of €550 (A). As the employee’s Average Net Weekly Pay is less than €586, the maximum weekly wage subsidy allowable for this employee is €385 (B), which is 70% of their Average Net Weekly Pay. The maximum additional payment an employer can make, to receive the full subsidy, is €165 (C), being the difference between the employees Average Net Weekly Pay €550 (A) and their maximum weekly wage subsidy €385(B).

In this example, the employer can make an additional payment up to value of €165 (C) and receive the full subsidy (see i below) for this employee, however if the employer’s additional payment exceeds this value then the subsidy must be reduced by the value of the excess (see ii below). This reduction may not be applied automatically by all payroll software packages. Where applicable, Revenue will apply subsidy reduction when calculating the subsidy refund that the employer will receive. In the transitional phase, this will be reflected in the balance payment due to be refunded to Revenue in the future (G).”

[3.11 – Is the wage subsidy taxable on the employee?]
“The payments are liable to income tax; however, the subsidy is not taxable in real-time through the PAYE system during the period of the Subsidy scheme. Instead the employee will be liable for tax on the subsidy amount paid to them by their employer by way of review at the end of the year. When an end of the year review takes place, it may be the case that an employee’s unused tax credits will cover any further liability that may arise. Where this is not the case, and should an Income Tax liability arise, it is normal Revenue practice to collect any tax owing in manageable amounts by reducing an individual’s tax credits for a future year(s) in order to minimise any hardship. Additionally, if an individual has any additional tax credits to claim, for example health expenses, this will also reduce any tax that may be owing.”

Link to Revenue’s Temporary Wage Subsidy Scheme Operational Guide–>  Click Here

COVID 19 Payroll Frequently Asked Questions (FAQ)

Our article on the COVID 19 Payroll Related Information will give you information on the background to the government support schemes and illness benefit and how to apply these in your Sage Payroll (Micropay). This article lists some of the most common questions that we have been asked in relation to this topic. (Please note, this article is for information only and while we have done our best to ensure accuracey at time of writing it is  subject to change, so please confirm any details with the relevant authorities before acting.)

Q.1. What should I do if I have to temporarily lay off staff?

If your company intends to open up after the pandemic and you feel that closure is temporary, you should enter into the ‘Wage Subsidy Scheme’. In this situation the employee needs to do nothing. The employer has to do all the work. (Qualify, register, calculate the 70/30 split in payroll, pay the wage, etc…) This is between the employer and Revenue. For this scenario – with regard to marking as a leaver –do nothing to the employees record (do not mark as leaver, do not mark as suspended).

Q.2. What should I do if I have to permanently lay off staff?

If the company has made a decision to ‘Let Go’ some or all staff permanently (as in: P45’d) then the relevant employee(s) should be marked as a leaver [as normal], not suspended. The employee then needs to apply for the ‘Pandemic Payment’ for themselves. This is between the individual and the revenue/DEASP. The ‘Pandemic Payment’ is an enhanced unemployment benefit, it is only available to people that are made officially ‘unemployed due to the COVID-19 pandemic and have been processed through the systems.


Q3. What if someone has worked overtime, additional hours etc. what would happen?

As per Revenue, when operating the scheme, the amount of subsidy claimed plus the amount of top up can not exceed the average net pay of the employee for the period January and February 2020. If the employer makes an additional payment greater than the difference allowed by the scheme (i.e. the employee receives more than the Average Net Weekly Pay) then the subsidy value refundable to the employer will be reduced by this excess amount when the refund reconciliation is performed by Revenue in due course. Therefore it would be in the employees / employers best interest to wait until the scheme is over.


Q4. Is the wage subsidy taxable on the employee?

The payments are liable to income tax; however, the subsidy is not taxable in real-time through the PAYE system during the period of the subsidy scheme. Instead the employee will be liable for tax on the subsidy amount paid to them by their employer by way of review at the end of the year.


Q5. What if my employee has multiple jobs, will they get multiple payments?

If an employee has multiple employments, each employer can operate the scheme based on 70% of each employee’s net weekly earnings.


Q6. How do Employers register for the Subsidy Scheme?

Employers, or their agents, apply to Revenue to operate the scheme by carrying out the following steps:

  • Log on to ROS myEnquiries,
  • Click Add A New Enquiry.
  • Select the category ‘Covid-19: Temporary Wage Subsidy’.
  • Read the “Covid-19: Temporary Wage Subsidy Self-Declaration” and press the ‘Submit’ button.
  • Revenue will issue a confirmation via myEnquiries and the employer can immediately operate the scheme.


Q7. Can paper filers use the scheme?

The scheme is open to employers who file electronically through ROS.


Q8. Is the scheme open to directors?

Yes, if directors are paid through the payroll system and are included in the relevant payroll submissions for an eligible employer then they are eligible to receive the wage subsidy.


Q9. Is the scheme open to self-employed as well as employees?

Self-employed individuals will be paid directly by DEASP under the COVID-19 Pandemic Unemployment Payment scheme rather than through this Revenue operated subsidy scheme.


Q10. What if an employer was refunded €203 in the Employer Refund Scheme, are they now due more?

The Temporary Wage Subsidy scheme is operational only from March 26, 2020 so they will not be due a further refund for submissions made up to that date. Revenue will transfer those employers who have registered for the Employer Covid-19 Refund scheme across to this new scheme and they are entitled to operate their payroll within the Subsidy Scheme from 26 March 2020.


COVID 19 – Payroll Related, Coronavirus Information.

COVID 19 – Payroll Related, Coronavirus Information.

As the current situation in Ireland is an ever changing landscape, details in this is article are subject to change. We will endeavour to keep it as up-to-date as possible. Any external links presented below are live, and you can click on them to go through to the relevant site, to help to confirm some of your queries.

This article relates to the initial “Transitional Phase” of the Temporary Wage Subsidy Scheme, for the latest information we have on the “Operational Phase” of this scheme, please click here –> Sage Payroll Software Update 23.2 for Operational Phase of the Covid19 TWSS (4th May 2020 Onwards)

We must advise that if you need clarity on particulars of your business relating to the wage subsidy scheme, you will need to contact revenue before you seek assistance with your payroll software. See Revenue contact details here –> Revenue Contact Us Link. If you are a Twitter user, you can follow them using the handle @RevenueIE –> Revenue Twitter Link

On 15 March 2020, the Government announced the implementation of exceptional measures, administered through the Department of Employment Affairs and Social Protection (DEASP), to enable workers who are temporarily laid off due to the COVID-19 (Coronavirus) pandemic to claim a special support payment called COVID 19 Pandemic Unemployment Payment. The payment was refundable under a scheme called COVID-19 Employer Refund Scheme. On the 24th March 2020, the Government changed this. They retracted the ‘COVID-19 Employer Refund Scheme’, and replaced it with the ‘Temporary COVID-19 Wage Subsidy Scheme’. Alongside that, the government also set up a ‘COVID 19 – Enhanced Illness Benefit’, claimable by those who are directed by a doctor to self isolate or by those who are ill with the virus.

The items covered in this article are:

  1. Information on ‘Temporary COVID-19 Wage Subsidy Scheme’.
  2. Information on ‘COVID 19 Pandemic Unemployment Payment‘.
  3. Information on ‘COVID 19 – Enhanced Illness Benefit’.
  4. Different Scenarios Employees might find themselves in.
  5. How to Process Wages for the ‘Temporary COVID-19 Wage Subsidy Scheme’ in Sage Payroll.
  6. Frequently Asked Questions (FAQ).


1. Information on ‘Temporary COVID-19 Wage Subsidy Scheme’ (Max €410 Weekly)
*This goes through your payroll system, and so it effects your payroll processing.
  • This a scheme which allow employers to pay their employees during the current pandemic.
  • It applies from Thursday 26th March 2020 onwards.
  • Employers will be refunded up to 70% of an employee’s wages – up to a level of €410.
  • The employer is expected to make their best efforts to maintain as close to 100% of normal income as possible for the subsidised period.
  • It replaces the DEASP’s ‘COVID-19 Employer Refund Scheme‘ which was announced on 15th March 2020.
  • Employers who registered for the ‘COVID-19 Employer Refund Scheme’ do not have to re-register for this new scheme.
  • It now applies where the employee has been laid off temporarily (zero hours).
  • A Top-Up payment is allowed to be paid by the employer.
  • It does not apply to workers who have been let go on a permanent basis – they instead qualify for the ‘COVID-19 Pandemic Unemployment Payment’ (see Below)
  • Under this Wage Subsidy Scheme, the employee does not need to do anything – but the employer must register to take part in the scheme.
  • This goes through your payroll system, and so it effects your payroll processing.

While some more detailed questions remain unanswered, we recommend to both read the articles in the links below, and talk to your accountant/HR contact before proceeding:
Click here to read GOV.ie article with further details –> Gov.ie Link
Click here to read Revenue.ie article with further details –> Revenue.ie Link

2. Information on ‘COVID 19 Pandemic Unemployment Payment’ (Currently €350 Weekly)
*This payment does not go through your payroll system, and so it does not effect your payroll processing.
  • This is a special Support Payment introduced due to the COVID 19 Pandemic, it is not an Illness Benefit.
  • It is claimable by both employees and self-employed who have been permanently laid off as a direct result of the COVID-19 (Coronavirus) pandemic. (ie: They have lost their jobs).
  • This payment will be in place for the duration of the pandemic.
  • It is paid at a flat rate of €350 per week (This was increased from €203 to €350 on the 24th March 2020).
  • In this scenario, the employee will need to register for the payment directly with the DEASP, and the payment will be made directly to the employee.)
  • To get this payment, the employer does not need to do anything – but the employee must register for the payment directly with the DEASP, and the payment will be made directly to the employee.

Again, while some more detailed questions remain unanswered, we recommend to both read the article in the link below, and talk to your accountant/HR contact before proceeding:
Click here to read GOV.ie article with further details –> Gov.ie Link


3. Information on ‘COVID 19 – Enhanced Illness Benefit’ (Currently €305 Weekly)
*Illness Benefit can optionally be put through your payroll system, usually depending on whether the employee is receiving the payment or the Employer.
  • This is an Illness Benefit.
  • It is claimable by those who are directed by a doctor to self isolate and therefore cannot attend work or by those who are ill with the virus and therefore cannot attend work.
  • With regard to payroll, it is treated the same as any illness benefit, the same as illness benefits prior to the COVID 19 Pandemic.
  • The Employee applies directly to the DEASP for this, and it is the employee who dictates who receives the payment (themselves or their employer).
  • It is not refundable under any scheme.
  • The employer cannot apply for this on behalf of the employee.

Again, while some more detailed questions remain unanswered, we recommend to both read the article in the link below, and talk to your accountant/HR contact before proceeding:
Click here to read GOV.ie article with further details –> Gov.ie Link


4. Different Scenarios Employees might find themselves in:

If you are confused about what applies in the different scenarios in which employees are finding themselves in, or you want to better advise employees, Citizens Information have put together this informative article – Citizens Information Link


5. How to Process Wages for the ‘Temporary COVID-19 Wage Subsidy Scheme’ in Sage Payroll

Full Details of processing for the ‘Temporary COVID-19 Wage Subsidy Scheme’ are detailed in the ‘Sage Link’ at the bottom of this section. But before you go there please read the following note:

Once you (as an employer) qualify for, and have registered for the Wage Subsidy Scheme with Revenue, the initial part of the process is to calculate 70% of the Average Net Weekly Wage per employee (Averaged over Jan & Feb weeks). You must use this figure from the start of the scheme.

To help you to figure out these amounts per employee, Sage have developed a report for use with the built in Report Writer in Sage Payroll. The article below will guide you through downloading and saving the report file into your system. You can then it run it and print\save it. It is advised to use this report to calculate the amounts, as they are calculated according to Revenues definition of Net Pay.

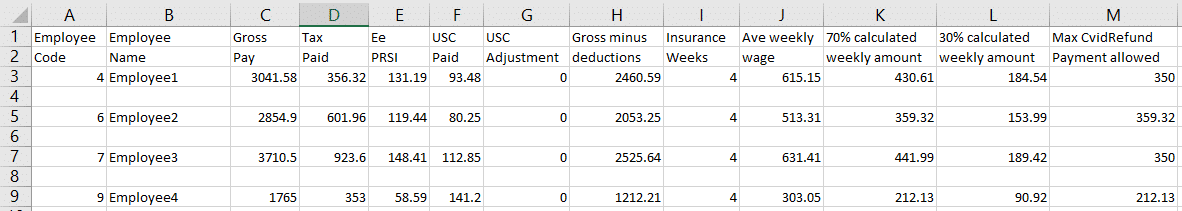
If you are an ‘ARW’ user (Advanced Report Writer) you will be happy to hear that Sage have developed a suitable report for that too. The article below will guide you through downloading and saving that file to your system. See sample in image below.

**[ARW is a separate program that runs outside of Sage Payroll]
**[We strongly advise that you work through the article below in full, reading each section as there may be particulars in it which lend to decision making during your process.] 

Click here for full instructions on how to process the Wage Subsidy in Sage Payroll –> Sage Link

The Sage Report will contain data similar to the image below:


Disclaimer: This article has been provided for information purposes only, While every effort has been made to ensure its accuracy at the time of writing, Pimbrook can not guarantee it will remain fully up to date. We would advise you to seek professional guidance on the latest information before acting on anything related to this topic.


Installing Sage Payroll (Micropay)

To install Sage Payroll (Micropay) follow these steps.

1. Ensure you have the following set up on the new computer to allow a successful installation of the payroll software, you may need to consult with your IT service provider to get these set up.

a. The Windows operating system has the latest updates installed.
b. The Windows login you are using has full administrator rights for that computer.
c. Any anti-virus and the “User Access Control” is turned off while installing so that they do not block the installation.

2. Run the installation program for the version of the software required (note: these can be found on the Pimbrook website download area). The program will bring you through the installation steps, continue through these taking the following options where appropriate depending on the installation set up required.

3.  Choose the installation type required, either “This Computer” for a standalone installation on the current computer only or “Client/Server” for a networked installation across multiple computers. If the “Client/Server” is required, install the “Server” first and then install the “Client” by running the install program again.

4. Select the installation settings when the screen below is shown,

5. Click “Typical” to install the software into the default directory paths or click “Custom” to display and change these directory paths.

6. The confirmation screen will be displayed showing the directory paths and other settings that will be used for the installation.

7. Click “Install” to perform the installation. (If you wish to change any of the settings click “Back”.).

8. If you are performing a “Client/Server” installation and you have completed the “Server” install, you will need to run the installation program again and follow the above steps but select “Client” at step 3 this time, otherwise you have completed the installation.

Moving Sage Payroll (Micropay) to a new computer

Moving your Sage Payroll (Micropay) from an old computer to a new computer involves an number of steps to install the software on the new machine and to copy over any local data.

The correct procedure is outlined below:

1. Take note of the “Program and Data Directories” from your current payroll installation on the old computer. This is shown under “Help –  System Information” in your Sage Payroll software.

2. If your Sage Payroll is installed on a “Standalone Computer”, copy these “Program and Data Directory” folders to the same locations on the new computer, if it is a Client/Server installation, copy just the “Program Directory” to the same location on the new computer. These folders are by year so you should copy all folders for the years that you require to the new computer, if you want them all, then copy the parent folder (e.g. “C:\ProgramData\Micropay Professional”
(Note: If the Sage Payroll Data Directory will be different on the new computer you will need to change the dataloc.ini file before you run the latest software. To do this go to the Sage Payroll “Program Directory” (as per 1 above) and browse to the dataloc.ini file. Copy this file out to the Desktop. Double click and open with Notepad. Change the path for the data, save the file and then copy into each year in the “C:\Program Files (x86)\Micropay Professional” or “C:\Program Files (x86)\Sage Payroll Irl” folder, if you are prompted that the file already exists, overwrite it).

3. If you have ROS certificates on the computer for payroll submissions then these may need to be copied to the new computer. You should find out where the certificates are on the old computer and copy these to the new computer, this is done as follows:

  • On the old computer, open Sage Payroll
  • Select “Retrieve RPNs”.
  • This will show you the folder path and file name of the ROS certificates (e.g. something like “C:\ROS\DigiitalROSCert.p12.bac”)
  • In Windows take a copy the ROS certificate file.
  • Move this copied certificate file to an ROS folder on the new computer (e.g. “C:\ROS”, you may need to create this folder).
  • After Sage Payroll is installed on the new computer (see step 4 below) you will need to set the ROS Digital Certificate when you first “Retrieve RPNs”. This is done by browsing to the new folder where the ROS certificate was copied to (see above) and selecting the certificate file. You will most likely have to enter your ROS password and save this.

4. Run the latest update of Sage Payroll (see Installing Sage Payroll) and check the Program Directory and Data Directory match the directories copied in 2 above during the installation.


Sage Payroll Software Update – Version 23.1

Sage Payroll update version 23.1 is now available.

What’s New:
  1. The primary change in this update relates to an increase in the national minimum wage by 30c to €10.10 and consequently the Class ‘A’ employer PRSI threshold will increase from €386 to €395. The two are not effective until 1st Feb 2020, but the update can be installed anytime before this date, as the software will only apply the new legislation changes to any payrolls dated February 2020 onwards.
  2. Update Timesheet “Over 65” Warning to “Over 66” (as 65 was the incorrect age.)
  3. “Set Period” will generate an error if the pay date is not within the current tax year.
  4. Employees who were not paid in the period, are now excluded from the Control Summary ‘Employee count’.
  5. In line with number 4 above, Employees with ‘no pay due’ will now be excluded from the Bank Transfer, Cash Dissection, Cheque Register & Credit Transfer Reports.
  6. Fix to Payments Report (Export to Excel) to include decimal places.


Installing the Update:

You may be prompted to install the update from your Sage Payroll software, if not you can download and install it from the Pimbrook download area. The procedure for this is the same as with any prior payroll update – see notes below:

  1. Ensure you have the correct version of software for the update. To see the version, open Sage Payroll 2020, click Help then click System Information. The version should begin with v23, if it does not, please install the payroll year end update, v23 – see here Sage Payroll Year End 2019 Update .
  2. Make a note of the Program Directory and Data Directory.
  3. Check that all of your payrolls have a status of End of Period (EOP) or Start of Period (SOP).
  4. Back up your payroll data.
  5. Close Sage Payroll 2020 and all other software.
  6. Log in to the computer as administrator (or as a user with administrator rights) and turn off any anti-virus and “User Account Control”.
  7. Download the update from the Pimbrook Download area by clicking here.
  8. Execute the downloaded file and follow the install steps, ensure the program and data directories are the same as noted in 2 above, for more information see our article on Sage Payroll Update Instructions and Preparation.


Important Note:

Please ensure that you install the update correctly, particularly if you are using a network installation and the data location is not on the same computer. If you find that some employees are on PRSI class A1 regardsless of their PRSI eligible pay then you probabaly have not applied the update to your data location (i.e. the server). If this occurs please reinstall the update correctly to all required locations (i.e. client and server computers).


Pimbrook Software
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.